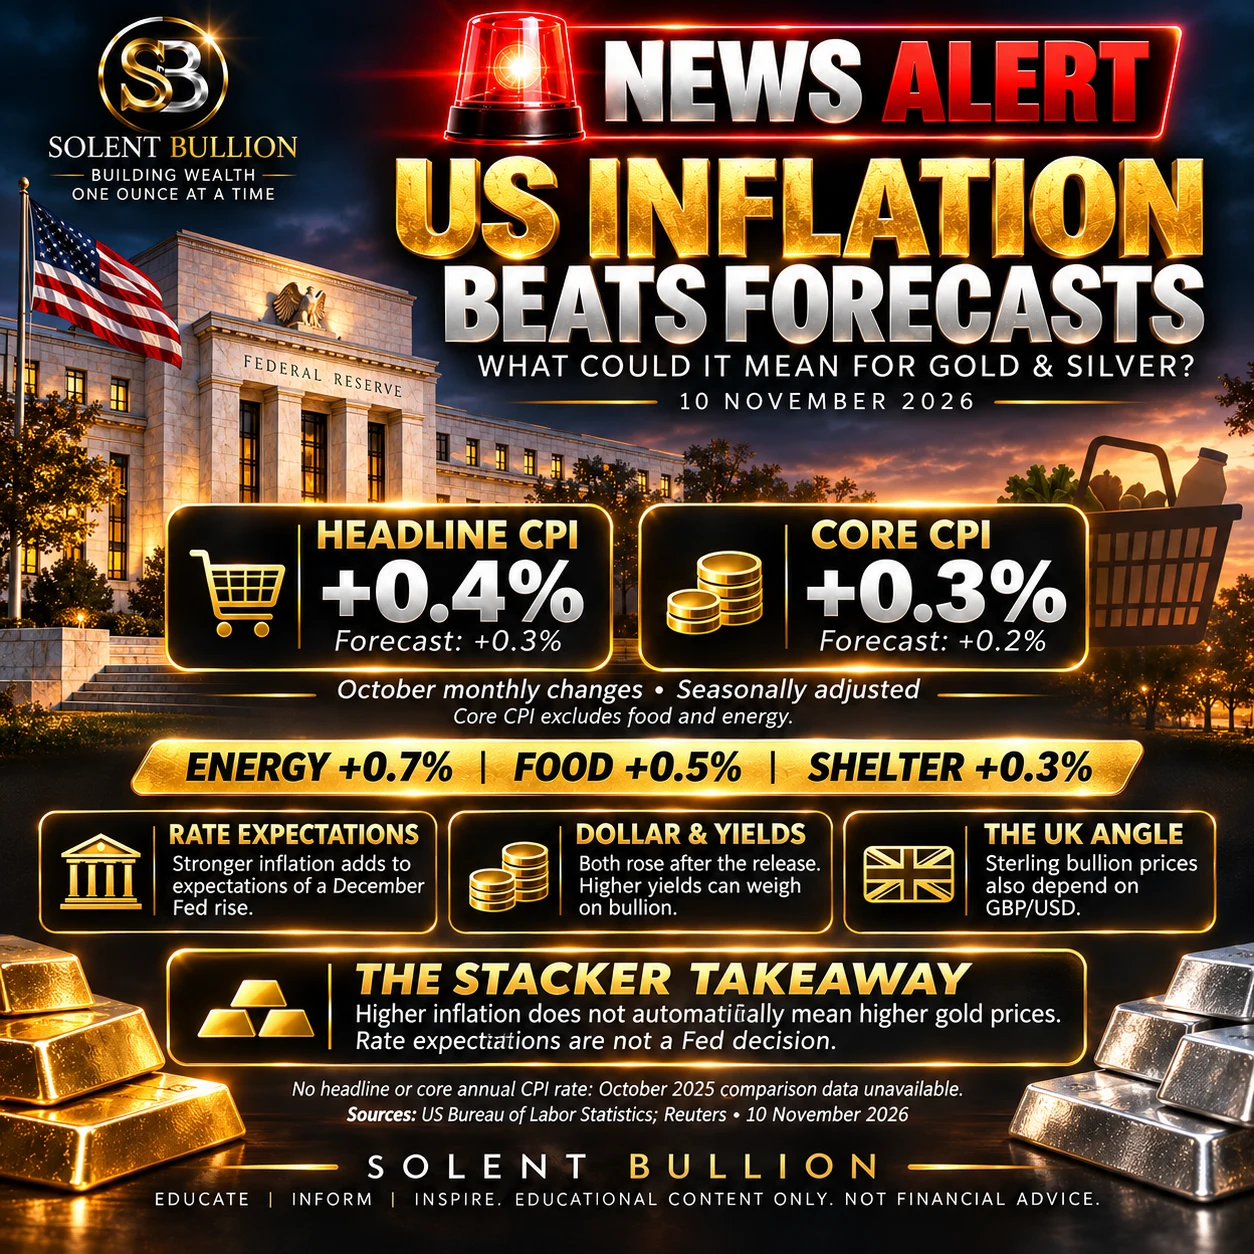
October CPI beat forecasts. Markets reassessed the rate outlook and the dollar and yields rose. The lesson for bullion owners: inflation, interest rates and currencies interact; no single figure guarantees the next price.
The inflation surprise, in context.
The US Bureau of Labor Statistics released October’s Consumer Price Index on 10 November 2026. Headline CPI rose 0.4% over the month; the measure excluding food and energy rose 0.3%. Both figures are seasonally adjusted. Energy rose 0.7%, food 0.5% and shelter 0.3%. [1]
Reuters’ pre-release economist forecasts were 0.3% for headline CPI and 0.2% for core CPI. The actual readings therefore exceeded both forecasts by 0.1 percentage point. Those forecasts come from reporting, not from the BLS. [2]
| Measure | Actual | Forecast |
|---|---|---|
| Headline CPI | +0.4% | +0.3% |
| Core CPI | +0.3% | +0.2% |
| Energy | +0.7% | Not shown |
| Food | +0.5% | Not shown |
| Shelter | +0.3% | Not shown |
Above forecast does not mean faster than the previous month: headline inflation had risen 0.6% in September. October’s increase was smaller, but larger than economists had expected. Core inflation matched its September monthly pace. This distinction matters when reading a headline about an inflation “surprise”. [1]
Why there is no usual annual comparison.
BLS says the October 2025 shutdown prevented collection of the comparison data needed for many October 2026 annual CPI readings. The usual headline and core year-on-year figures are therefore unavailable. This is a gap in the comparison base, not evidence of zero annual inflation. [1]
Multiplying one monthly figure by twelve would not recover the missing official annual observation. We have not done that here. Keep monthly movements, forecasts and annual measures separate; each answers a different question.
The first response was about rates and currencies.
Reuters reported that the dollar and Treasury yields rose after the release, alongside stronger expectations of a December Federal Reserve rate increase. [3] This article is a dated explanation of that reaction, rather than a live price update or a closing-market report.
A market expectation is not a policy decision. Investors can change their view before the Fed meets, and later information can change that view again. The CPI release itself does not announce a rate increase, its size or a guaranteed path for bullion.
New information
Inflation exceeds the forecast.
Reassessment
Markets reconsider the rate outlook.
Repricing
Yields, currencies and metals respond.
That sequence is an explanatory framework. It does not prove that one release explains every move in every asset. Different markets can absorb the same information differently, and intraday reactions can reverse.
Why higher inflation can pressure gold.
Gold does not pay interest. A higher return on interest-paying assets can therefore increase the opportunity cost of holding it. Chicago Fed research examines expected long-term real interest rates, inflation expectations and concerns about economic conditions as drivers of gold. [4]
The word “real” matters: it means allowing for inflation. A rise in a nominal bond yield does not, by itself, tell us how much its expected inflation-adjusted return has changed. For a simplified illustration, a 4% nominal yield and 2% expected inflation imply roughly a 2% real yield; a 5% nominal yield and 3% expected inflation imply roughly the same real yield. These are invented examples, not current market readings.
There can be competing interpretations of an inflation surprise. One is concern about purchasing power, which can support interest in gold. Another is anticipation of tighter monetary policy, which can make alternative returns more attractive. The balance can vary over time. Treat “inflation up, gold up” as an incomplete explanation, not a dependable rule.
It is “What changed in expected rates, real yields and currencies?”
This is why a long-term reason for owning a physical asset can coexist with a short-term fall in its quoted price. Neither an inflation release nor a single market session establishes what gold must do next.
The dollar adds another moving part.
International metal prices are commonly discussed in US dollars. As a conversion matter, a stronger dollar makes a fixed dollar price more expensive in a currency that weakens against it. That can create a headwind for demand; it is not a promise of a particular price move.
Dollar strength and the metal price can also move together, or respond to the same underlying news. Avoid counting two related market moves as two independent proofs of a forecast. For a UK owner, the particular exchange rate used to convert dollars into pounds matters more than a broad statement that “the dollar rose”.
Silver has an industrial side as well.
Silver shares the interest-rate and currency channels, but it also has uses in electronics and electrical equipment. The Silver Institute describes applications including switches, circuit boards and conductive inks. [5]
That creates another set of questions: what is happening to manufacturing activity, orders and demand for products that use silver? Tighter financial conditions could affect those expectations, but this CPI report does not measure silver consumption, mine supply or retail coin availability.
It would therefore be misleading to translate the inflation surprise directly into a claim of a silver shortage or a guaranteed silver-price move. Gold and silver need their own evidence even when both respond to the same macroeconomic headline.
A dollar move is not your sterling result.
A useful starting point is: GBP metal value = USD metal price ÷ GBP/USD, where GBP/USD means dollars per pound. This is a currency conversion, before physical-product costs.
Consider a deliberately simplified example. A metal reference price of $4,000 per troy ounce, at $1.25 per pound, converts to £3,200. Suppose the dollar metal price then falls 2% to $3,920 while sterling also falls 2% to $1.225 per pound. Dividing $3,920 by 1.225 still gives £3,200.
| Measure | Starting point | After the changes |
|---|---|---|
| Dollar metal price / troy oz | $4,000 | $3,920 |
| GBP/USD (dollars per pound) | 1.250 | 1.225 |
| Converted GBP value / troy oz | £3,200 | £3,200 |
The currency move offsets the metal-price fall in this particular example. If sterling were unchanged, the sterling metal value would fall 2%; if sterling strengthened instead, the fall in pounds would be greater. Real-world movements will not necessarily line up so neatly.
A dealer’s physical coin or bar quote is a further step. Premiums, the buy/sell spread, delivery and other applicable charges can change the amount paid or received. Compare the same fine-metal weight, currency and observation time, then examine the full purchase and buyback quotes. The conversion is not a retail offer.
Follow evidence, rather than a single headline.
- Subsequent inflation releases: is the surprise repeated, revised or offset by later information?
- Fed communications and decisions: separate an individual view or market expectation from an announced policy decision.
- Nominal and real yields: check which measure a commentary actually means.
- GBP/USD: compare currency and metal movements over the same time period.
- Physical-market quotes: distinguish international reference prices from actual product premiums and buyback terms.
Stronger-than-expected inflation changes the questions markets ask about rates and currencies. It does not settle gold’s or silver’s future direction. For UK bullion owners, the useful comparison includes the metal, the pound and the full cost of the physical product.
Read the evidence behind the analysis.
Sources checked on 10 November 2026. Reported facts are linked separately from Solent Bullion’s explanations. Numerical teaching examples are invented and explicitly labelled. The artwork is illustrative. This is educational content, not a personalised recommendation or price forecast.
- US Bureau of Labor Statistics — October 2026 CPIPrimary data, released 10 November 2026. This rolling release URL may change when a later report is published.
- Reuters — Pre-release October CPI forecastsEconomist forecasts, dated 10 November 2026; distinguished from actual BLS results.
- Reuters — Gold, the dollar and yields after CPIDeveloping market report dated 10 November 2026; not a closing-price source.
- Federal Reserve Bank of Chicago — What Drives Gold Prices?Background research, November 2021.
- The Silver Institute — Silver in electronicsBackground on industrial uses; no current demand totals inferred.